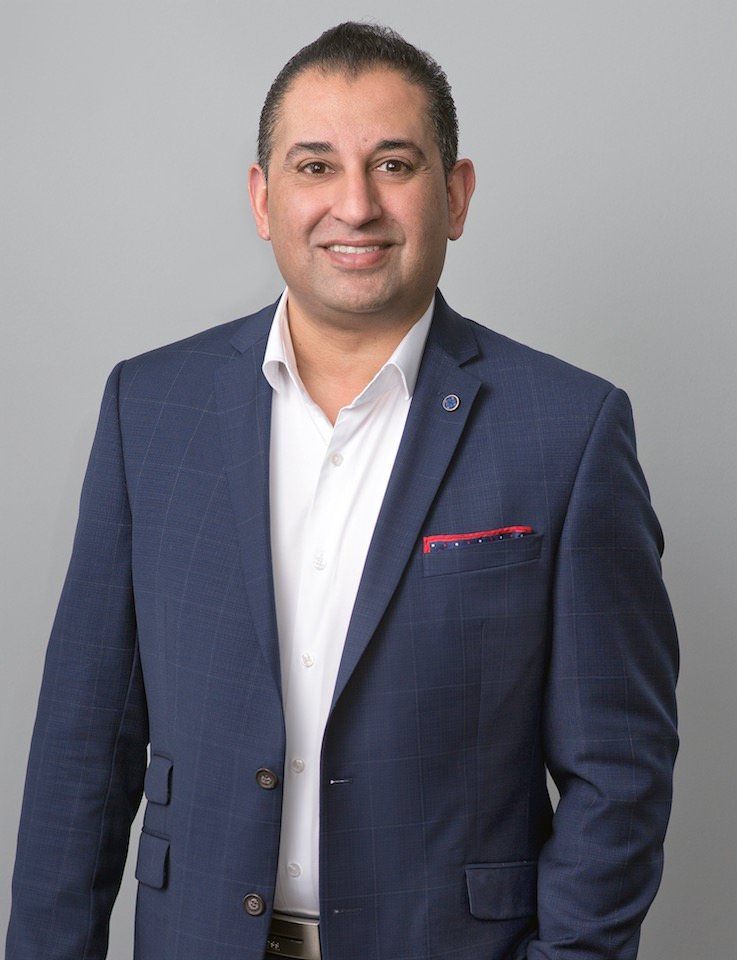
Mick Gill

Accredited Mortgage Professional

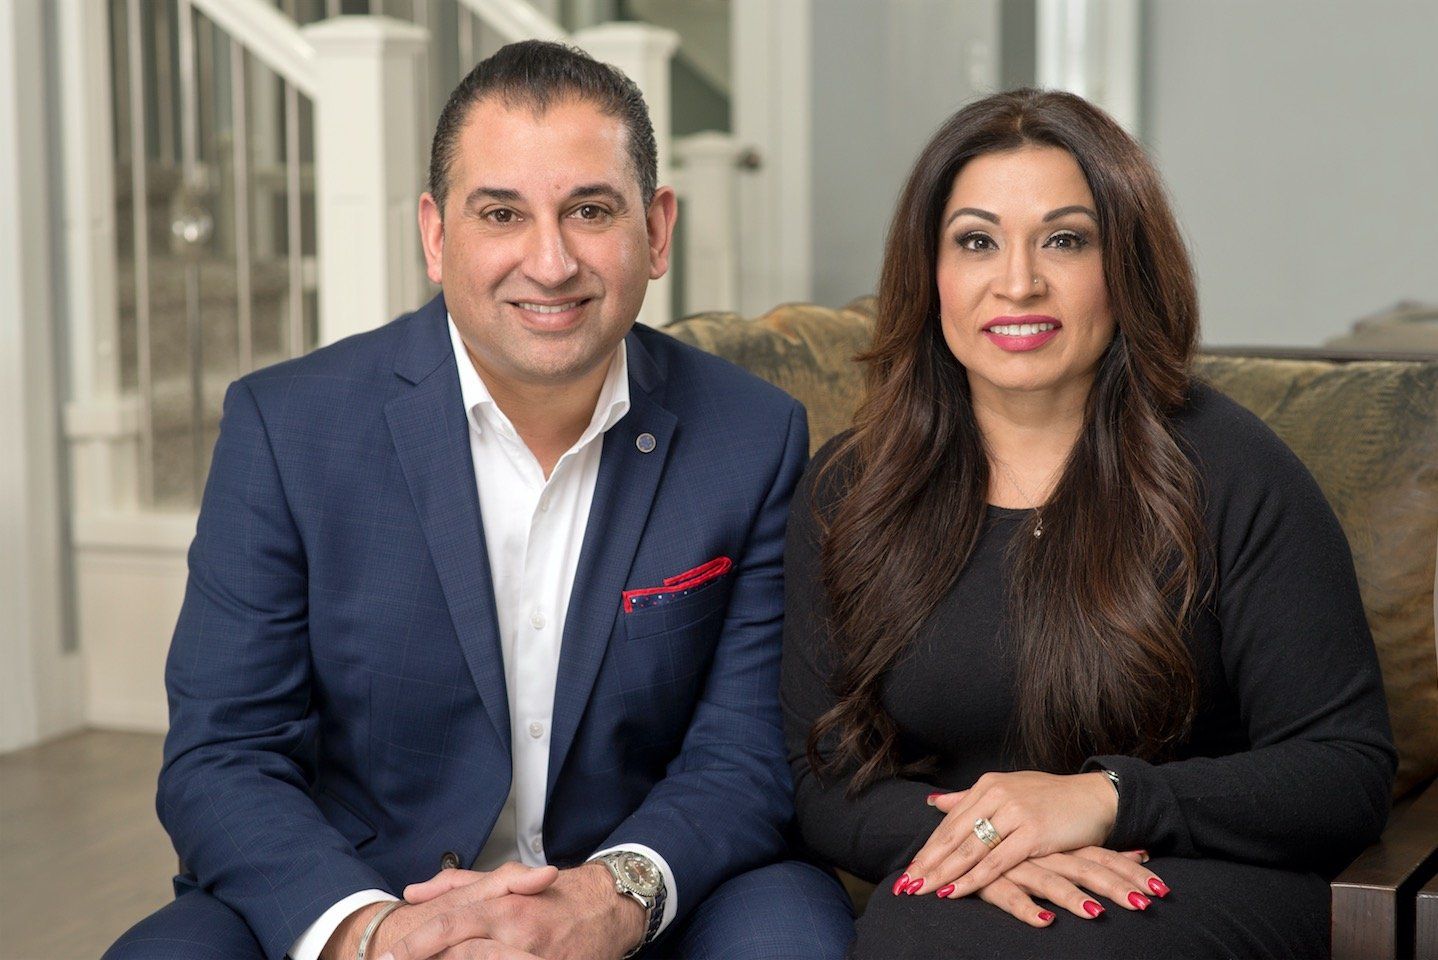
With over 20 years mortgage lending experience, I advise my clients with the best solutions for all their financing needs. Alongside my wife Sheila, we build and maintain long term relationships with our clients helping with their immediate and future needs for themselves and their families. As part of a large network of mortgage professionals, we’re able to offer the very best in mortgage products and rates.


Our goal is to keep the mortgage process as simple and stress free as possible.
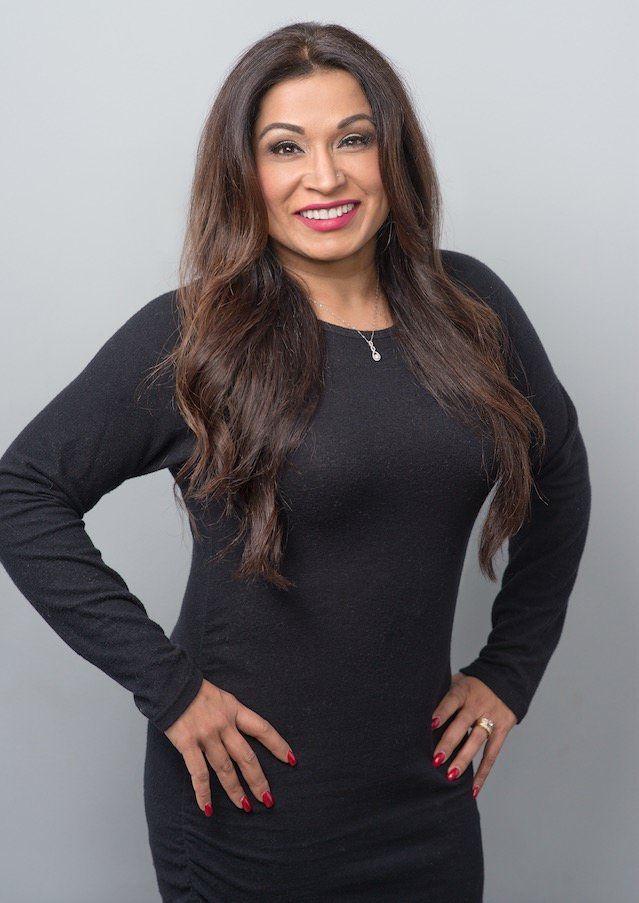
Sheila Gill

Mortgage Professional

Sheila started her mortgage career in September 2006 as an assistant to her husband Mick and officially joined Mick in May 2007. She brings 17 years of experience in dealing with the general public as a government employee. She thrives on providing the best service possible to all her clients and finding the right solution to fit their needs. 


She loves to workout and watch basketball, football and hockey. 
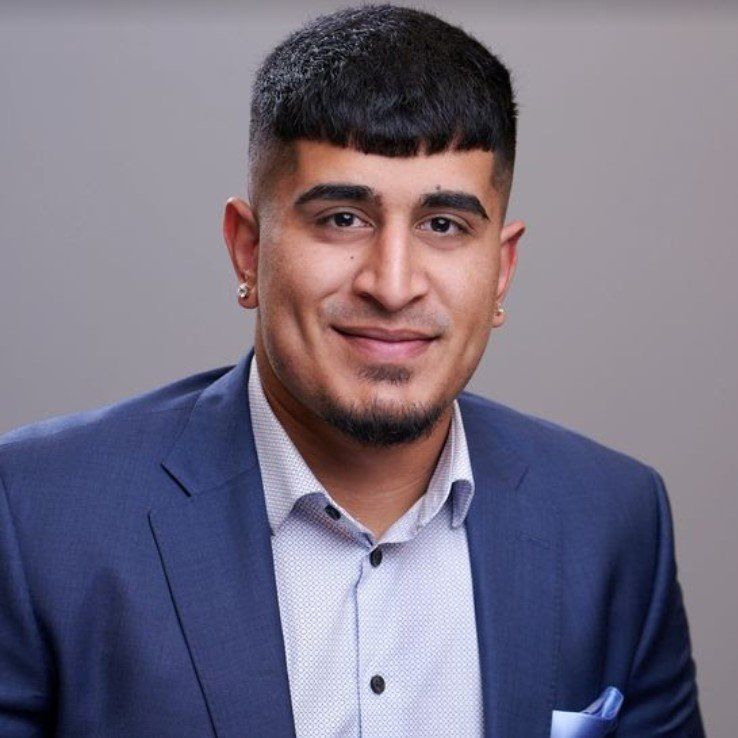
Dylan Gill

Mortgage Broker

Dylan is a lifelong Surrey resident and started with the Gill Team in March of 2020. Dylan enjoys the opportunity to help clients achieve their goals and strives to build long term relationships. 


Dylan has been a broker for 5 years, specializing in Commercial.


Dylan is an avid sports fan. If he isn’t watching the games, he will be out there playing football, hockey, basketball & golf.


Mortgage financing doesn't have to be difficult. We can do this together, here's the plan...

STEP ONE
Get Connected 

The best place to start is to connect with us directly. The mortgage process is personal, and it can be daunting. Our commitment to you is that we'll listen to all your needs, assess your financial situation and provide you with a plan to move forward. 

STEP TWO
Evaluate Options

Once we’ve had a look at your financial situation, we’ll consider a variety of mortgage options, we’ll outline what documents are necessary to qualify for a mortgage, negotiate with the lenders on your behalf and arrange the mortgage that best suits your needs.

STEP THREE
Rest Easy

Once we’ve arranged the mortgage product that best suits your needs, you’re not alone. We're your mortgage professionals for life. If you’ve got questions in the years to come, we're always available to make sure that your mortgage is working for you and not the other way around!

Mortgage Services

Customer Care

We believe that our responsibility as mortgage experts goes well beyond simply arranging mortgage financing. Our job is to ensure our clients feel confident in the mortgage process and make decisions that best suit them.


Education

In order for our clients to feel confident about the mortgage process and make the best decisions for them, they have to feel at ease and be able to ask questions. We stay in touch throughout the entire process, provide lots of information up front, but also make ourselves available all the time! 


Here For You

Although we are independent mortgage experts, we do collaborate and work together… because two heads are better than one! Please feel free to reach out to either of us with questions. We would love to hear from you!

Recently From the Blog
By Team Gill • November 17, 2026
Buying a home is one of the biggest financial commitments you’ll ever make. That’s why lenders want to be sure you can handle your mortgage payments—not just today, but also if interest rates rise in the future. This is where the mortgage stress test comes in. Many Canadians hear the term but aren’t entirely sure what it means or how it affects them. Let’s break it down in plain language. What Is the Mortgage Stress Test? The stress test is a rule introduced by the federal government that requires all mortgage applicants to qualify at a higher rate than the one they’ll actually pay. Currently, you must qualify at the greater of your contract rate + 2% or the benchmark qualifying rate (set by the Office of the Superintendent of Financial Institutions). For example: If your lender offers you a 5-year fixed mortgage at 5.25%, you must show you could still afford the payments at 7.25% . Even if rates don’t rise that high, the stress test ensures you won’t be overextended if they do. Why Does It Matter? The stress test protects both borrowers and lenders by: Preventing over-borrowing : It ensures you don’t take on more debt than you can realistically handle. Preparing for rate hikes : With interest rates fluctuating, it’s a safeguard against sudden increases. Strengthening financial stability : It lowers the risk of defaults, protecting the housing market as a whole. While it can sometimes feel like a barrier—reducing the amount you qualify for—it’s ultimately designed to keep you from becoming “house poor.” How Does It Impact Buyers? The stress test can significantly affect your homebuying budget. For example, without it, you might qualify for a $600,000 mortgage, but with the stress test applied, you may only qualify for $500,000. That doesn’t mean your dream of homeownership is out of reach—it just means you may need to adjust expectations or explore other strategies, such as: Increasing your down payment Paying down existing debts Considering alternative lenders who may have different qualification standards Why Work With a Mortgage Professional? Every lender applies the stress test, but not every lender views your application the same way. An independent mortgage professional can: Shop multiple lenders to find the best fit Run affordability scenarios at different rates Help you understand how much house you can truly afford—without stretching your finances too thin The Bottom Line The mortgage stress test isn’t meant to stop you from buying a home—it’s there to protect you from financial strain down the road. By understanding how it works and planning ahead, you can make smarter choices and buy with confidence. If you’re thinking about purchasing a home, refinancing, or simply want to know how the stress test affects your options, connect with us today. We’ll help you stress-test your budget and find the mortgage solution that works best for you.
By Team Gill • November 3, 2026
You’ve found the right home, your offer’s been accepted, and your financing is approved—congratulations! But before you can pick up the keys and celebrate, there’s one more important stage: the closing process. Closing is the final step in your homebuying journey, where all the paperwork, legal details, and financial transactions come together. It can feel overwhelming if you don’t know what to expect, but with the right preparation, closing can be smooth and stress-free. Here’s a step-by-step guide to help you understand the process. Step 1: Hire a Lawyer or Notary A real estate lawyer (or notary, depending on your province) handles the legal side of closing. They will: Review the purchase agreement and mortgage documents Conduct a title search to confirm the seller has the legal right to sell the property Ensure the mortgage lender is properly registered on the title Handle the transfer of funds between you, the lender, and the seller Your lawyer or notary will be your main point of contact during closing, so choose one you trust and who communicates clearly. Step 2: Finalize Your Mortgage Your lender will send the mortgage instructions directly to your lawyer or notary. At this stage: You’ll provide proof of property insurance (lenders require this before releasing funds) You’ll confirm your down payment and closing costs are available in your lawyer’s trust account The lawyer will prepare all documents for your review and signature Step 3: Pay Closing Costs Closing costs typically range from 1.5% to 4% of the purchase price. These can include: Legal fees Title insurance Land transfer tax (where applicable) Adjustments for property taxes or utilities prepaid by the seller Home inspection or appraisal fees (if not already paid) Your lawyer will provide a final statement of adjustments so you know exactly how much is due on closing day. Step 4: Sign the Paperwork A few days before closing, you’ll meet with your lawyer or notary to sign all the necessary documents, including: Mortgage agreement Title transfer Insurance confirmations Statement of adjustments Bring valid government-issued ID to this appointment. Step 5: Transfer of Funds On the day of closing: Your lender sends the mortgage funds to your lawyer Your lawyer combines these funds with your down payment and pays the seller Legal ownership of the property is transferred into your name The lender is registered on title as a secured creditor Step 6: Get the Keys! Once the paperwork is filed and the funds have cleared, your lawyer will confirm that the transaction is complete. You’ll then get the keys to your new home—officially making it yours. The Bottom Line The closing process is a series of important steps, but with the right team in place, it doesn’t have to be stressful. By working closely with your mortgage professional and lawyer, you’ll have guidance every step of the way—from signing the documents to turning the key in the front door. If you’d like help preparing for the closing process—or want a clear breakdown of your own closing costs— connect with us today.
By Team Gill • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.

We Keep Our Blog Up To Date So You Can Stay Informed!

Read More From The Blog